Structured Settlement vs Lump Sum: Which Is Better?
- Structured settlements provide financial security and tax-free income but lack flexibility.
- Lump sums offer immediate access to cash but require discipline to avoid overspending.
- Tax treatment is similar: both are generally tax-free if received as compensation for physical injuries.
If you're negotiating a personal injury settlement, one of the biggest decisions you'll face is whether to take a structured settlement or a lump sum. Each option has real trade-offs, and the right choice depends on your personal circumstances, financial habits, and long-term goals.
This article explains how each payout method works, the pros and cons, and the factors you should consider before deciding. Remember, this is general information, not legal advice. Always consult with an attorney or financial advisor before making a final decision.
What is a structured settlement?
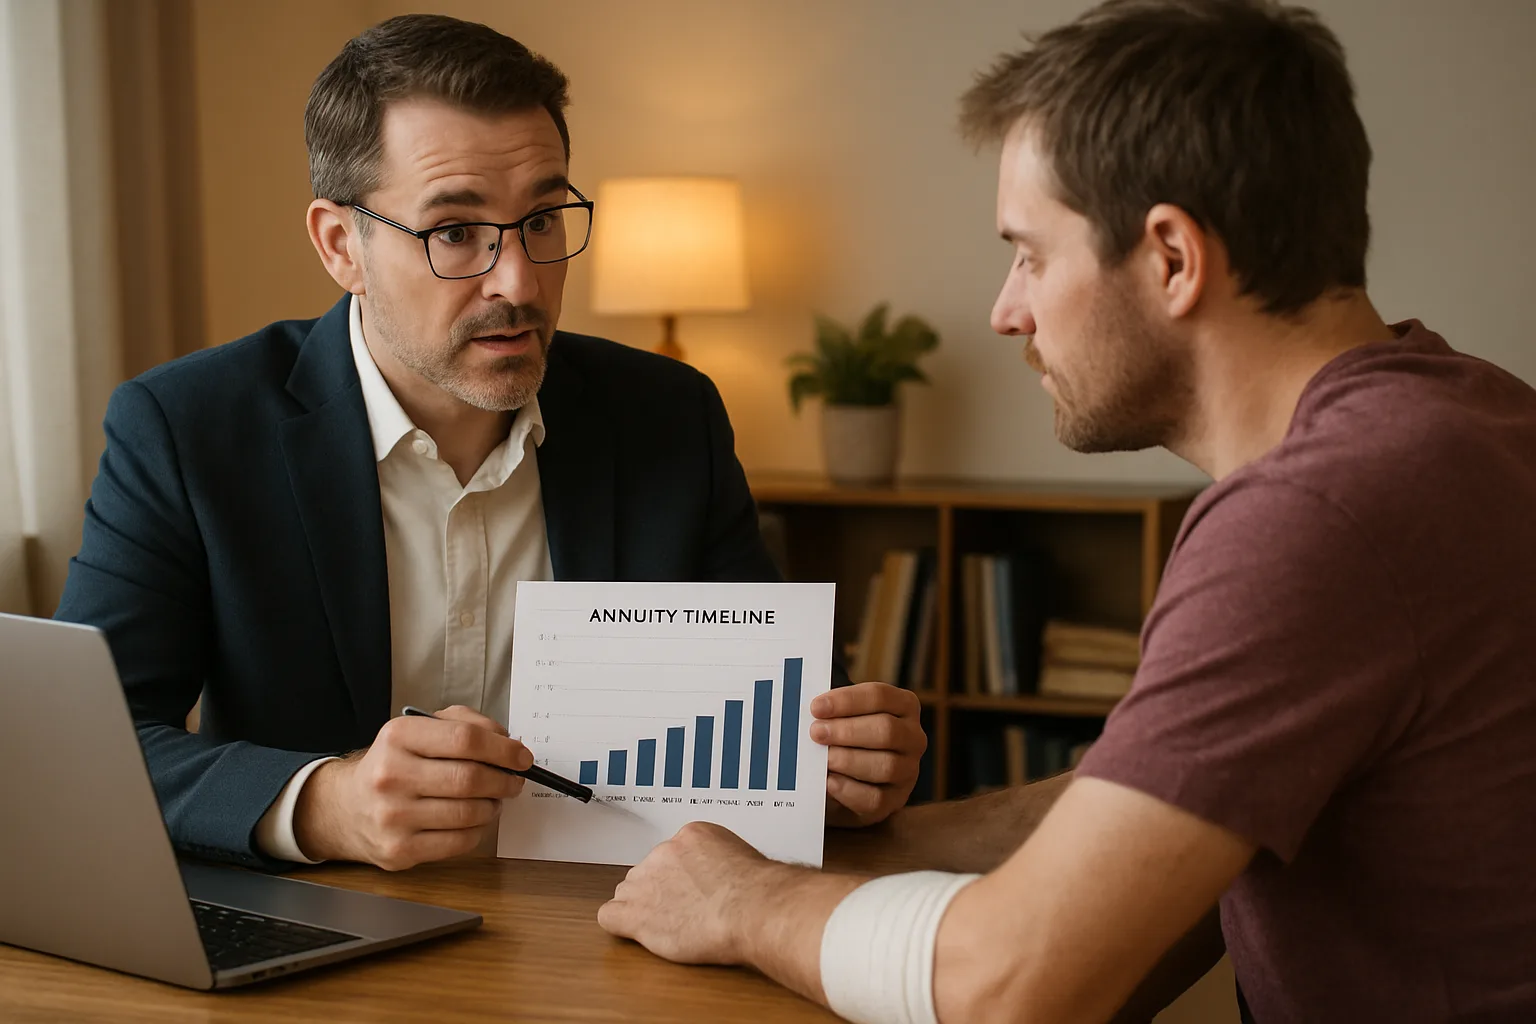
A structured settlement is a financial arrangement where you receive your compensation in periodic payments over time, rather than all at once. The defendant (or their insurance company) purchases an annuity from a life insurance company, which then makes the payments to you according to a schedule you negotiate.
Payments can be monthly, quarterly, or annually. They can also include lump sums at certain milestones (e.g., every five years) or a balloon payment at the end. The schedule is customized to your needs.
The key feature of a structured settlement is that the payments are guaranteed by the insurance company and are backed by state guaranty associations. You cannot outlive the payments — if you die, the remaining payments go to your beneficiaries.
How structured settlement payments work in practice
When you agree to a structured settlement, the defendant's insurer buys an annuity from a highly rated life insurance company. That annuity generates the payments you receive according to the schedule you negotiated.
For example, if you settle for $500,000, you might receive $2,000 per month for 20 years, plus a $50,000 lump sum every five years for education or home repairs. The total payments over time could exceed the original settlement amount due to interest.
The insurance company assumes the investment risk. If the annuity underperforms, the insurer must still make the promised payments. This gives you a guaranteed income stream regardless of market conditions.
What is a lump sum settlement?
A lump sum settlement is a single, upfront payment of the entire settlement amount. You receive the money at once, and you have full control over how to use, save, or invest it.
Lump sums are the default in many personal injury cases unless both parties agree to a structured settlement. Once you accept a lump sum, the case is closed, and you have no further obligation from the defendant.
The main advantage is immediate access to cash. The main risk is that you might spend it too quickly or make poor investment decisions, leaving you without funds for future needs.
Common uses for lump sum settlements
People often use lump sums to pay off high-interest debt, such as credit cards or medical bills. Others use the funds to make a down payment on a home or start a small business.
For example, a plaintiff with $300,000 in medical debt might use a $400,000 lump sum to eliminate that debt and invest the remaining $100,000. This immediate debt relief can reduce financial stress and improve credit scores.
However, without a solid plan, a lump sum can disappear quickly. Studies show that many recipients spend their entire settlement within five years, leaving them without resources for future medical needs.
Structured settlement: pros and cons
Pros of structured settlements
- Tax-free payments. Under Section 104 of the Internal Revenue Code, periodic payments from a structured settlement are exempt from federal income tax. That includes the interest earned on the annuity.
- Financial security. You get a steady, predictable income stream that can cover ongoing medical expenses, living costs, or education. You can't outspend the schedule.
- Protection from poor decisions. If you're worried about your ability to manage a large sum, a structured settlement removes the temptation to overspend or make risky investments.
- Customizable schedule. You can design payments to match your expected needs — for example, larger payments during college years or smaller payments during retirement.
- Creditor protection. In many states, structured settlement payments are exempt from creditors and bankruptcy.
Cons of structured settlements
- Inflexibility. Once the settlement is signed, you cannot change the payment schedule. If an unexpected expense arises, you may not have access to enough cash.
- Lower total payout. The total amount you receive over time is often less than what you could earn by investing a lump sum yourself — especially if you're a savvy investor.
- No access to principal. You cannot withdraw a large sum for a major purchase (like a house) unless you sell the structured settlement — which comes with high costs.
- Inflation risk. Fixed payments lose purchasing power over time if inflation rises. Some structured settlements include cost-of-living adjustments, but not all.
- Counterparty risk. Although rare, the insurance company could fail. State guaranty associations provide some protection, but it's not unlimited.
Lump sum: pros and cons
Pros of lump sum settlements
- Immediate access to cash. You can use the money for any purpose — paying off debt, buying a home, starting a business, or investing.
- Investment potential. If you're disciplined, you can invest the lump sum and potentially earn a higher return than the annuity's interest rate.
- Flexibility. You can adapt to changing circumstances without needing approval from anyone.
- Simplicity. One payment, one tax event, and the case is closed. No ongoing administration.
Cons of lump sum settlements
- Risk of overspending. Many people who receive a large lump sum spend it quickly, sometimes within a few years. This can leave you without funds for future medical needs.
- Investment risk. If you invest poorly, you could lose a significant portion of your settlement. There's no guaranteed return.
- Creditor exposure. A lump sum is an asset that creditors or bankruptcy courts can seize.
- Tax complexity. While the settlement itself is tax-free, any interest or investment gains are taxable. You'll need to manage tax reporting.
Tax implications: which option is taxed?
Both structured settlements and lump sum payments are generally tax-free if they are received as compensation for physical injuries or sickness. This is governed by 26 USC §104. The exclusion applies to the entire amount, including any interest earned on the structured settlement annuity.
However, if your settlement includes compensation for non-physical injuries (like emotional distress without physical injury) or punitive damages, those portions may be taxable. Also, if you later invest a lump sum, any interest, dividends, or capital gains are taxable. Structured settlement payments remain tax-free even if they include interest.
One nuance: if you sell your structured settlement to a factoring company, the proceeds from the sale may be partially taxable. You should consult a tax professional if you're considering that route.
Tax reporting requirements for each option
With a structured settlement, you typically receive a Form 1099-INT or 1099-R each year showing the payments. However, you do not report them as income because they are tax-free.
With a lump sum, you receive the entire amount tax-free at the time of settlement. But if you invest the money, you must report and pay taxes on any interest, dividends, or capital gains generated.
For example, if you invest a $200,000 lump sum in a stock portfolio and earn $10,000 in dividends, that $10,000 is taxable. In contrast, a structured settlement paying $20,000 per year remains entirely tax-free.
When structured settlements make more sense
Structured settlements are often recommended in these situations:
- Catastrophic injury. If you have permanent disabilities or ongoing medical needs, a steady income stream ensures you can cover future costs.
- Minors. Courts often require structured settlements for children to protect the funds until adulthood.
- Financial inexperience. If you're not confident in managing a large sum, a structured settlement prevents mistakes.
- Spending concerns. If you have a history of impulsive spending or addiction, periodic payments reduce the risk of running out of money.
- Long-term care needs. For injuries requiring lifelong care, a structured settlement can be tailored to match expected expenses.
Real-world example: catastrophic injury
Consider a plaintiff who suffers a spinal cord injury requiring $5,000 per month in ongoing medical care. A structured settlement providing $6,000 per month for life ensures those costs are always covered.
If the same plaintiff took a $1 million lump sum and spent $200,000 on a home, $100,000 on a car, and $50,000 on vacations, they might have only $650,000 left for future care. That amount could be exhausted in just over a decade.
With a structured settlement, the payments continue regardless of how much money remains. This protects the plaintiff from running out of funds during their lifetime.
When lump sum makes more sense
A lump sum may be better if:
- You are a savvy investor. If you have experience managing money and can earn a higher return than the annuity rate, a lump sum could grow more over time.
- You need to pay off debt. If you have high-interest debt (credit cards, medical bills), paying it off immediately can save you money.
- You have a short life expectancy. If your injury reduces your lifespan, a lump sum allows you to enjoy the full value now.
- You want to buy a home or start a business. Large purchases are easier with a lump sum than with periodic payments.
- You prefer simplicity. One payment and done — no ongoing paperwork or monitoring.
Real-world example: debt elimination
Imagine a plaintiff with $150,000 in credit card debt at 20% interest. A $200,000 lump sum allows them to pay off the debt immediately, saving $30,000 per year in interest.
They can then invest the remaining $50,000 in a diversified portfolio. Over 10 years, that $50,000 could grow to $100,000 or more with compound interest.
In contrast, a structured settlement paying $1,500 per month would take over eight years to pay off the debt, during which interest charges would accumulate. The lump sum provides a faster path to financial freedom.
Can you convert a structured settlement to lump sum?
Yes — but you'll pay a steep price for that flexibility. The process is called a structured settlement factoring transaction, and it works like this: a factoring company buys the right to receive your future payments, then gives you a reduced lump sum today. The difference between what they pay you and what they'll collect is their profit.
The Structured Settlement Protection Act (SSPA), enacted at the federal level and mirrored by most states, requires court approval before any sale can proceed. A judge must find the transaction in your "best interest" — but courts approve most petitions when paperwork is complete, so that review is often more procedural than protective.
The real math: how much do you actually lose?
Factoring companies apply a discount rate — essentially an interest rate in reverse — to calculate how much to pay you today. Industry discount rates typically range from 9% to 18% annually. That sounds manageable until you run the numbers.
Say you have a structured settlement paying $2,000 per month for the next 15 years — a total future value of $360,000. At a 12% discount rate, a factoring company might offer you around $170,000 to $190,000 today. You walk away with roughly half the total value you were owed.
| Future payments total | Discount rate | Lump sum offered | You lose |
|---|---|---|---|
| $360,000 (15 yrs) | 9% | ~$215,000 | ~$145,000 |
| $360,000 (15 yrs) | 12% | ~$180,000 | ~$180,000 |
| $360,000 (15 yrs) | 18% | ~$140,000 | ~$220,000 |
The longer the remaining payment period, the worse the deal gets. A 5-year remaining stream loses far less value than a 20-year one at the same discount rate.
The court approval process, step by step
Most states require the following before you can sell your structured settlement:
- Independent legal counsel. You must consult an attorney — separate from the factoring company's lawyer — who advises you on the transaction. Some states require this in writing.
- Disclosure statement. The factoring company must provide a written disclosure at least three days before signing. It must clearly state the discount rate, the lump sum offered, and the total future payments you're giving up.
- Court petition. The factoring company files a petition in your local court. You must appear or submit an affidavit explaining why you need the money now.
- Best-interest finding. The judge reviews whether the sale is in your best interest — considering your financial situation, the purpose of the original settlement, and whether you have dependents.
- Waiting period. Most states require a 10-30 day waiting period after filing before the hearing. The entire process typically takes 45 to 90 days.
Courts can and do deny petitions — most often when the plaintiff can't articulate a genuine financial need, or when the discount rate is unusually high. A 2019 analysis by the Consumer Financial Protection Bureau found that many factoring transactions were approved despite discount rates well above market norms.
Warning signs of predatory factoring companies
Not all factoring companies play fair. Watch for these red flags:
- Pressure tactics. Legitimate companies give you time to think. If someone is urging you to "sign today before the offer expires," walk away.
- Upfront fees. Reputable companies deduct fees from the proceeds, not before. Any demand for upfront payment is a scam signal.
- Discount rate not disclosed clearly. Federal law requires full disclosure. If you have to ask what the rate is, that's a problem.
- Promises to bypass court approval. This is illegal. Any company claiming they can skip the court process is misrepresenting the law.
- Targeting during financial crisis. Some companies specifically market to people in acute financial distress — hospitals, debt collectors, and bankruptcy courts are common sources of leads. Take time to get competing offers.
How to get the best offer if you decide to sell
If you've decided the sale makes sense for your situation, don't accept the first offer. Here's how to negotiate:
- Get at least three competing quotes. Discount rates vary significantly between companies. A single phone call to a second company can save you tens of thousands of dollars.
- Sell only a portion. You don't have to sell the entire payment stream. Selling just 3-5 years of payments gives you immediate cash while preserving the majority of your future income.
- Use an independent broker. A structured settlement broker (not affiliated with a factoring company) can shop your payment stream to multiple buyers and negotiate on your behalf.
- Time the sale. Interest rates affect discount rates. When market interest rates are lower, factoring companies offer better terms. Selling during a low-rate environment can meaningfully increase your payout.
Tax implications when you sell
When you received the original structured settlement, the payments were tax-free under IRC §104. When you sell those payments, the tax treatment changes. The IRS treats the sale as a sale of a capital asset. Any gain — the difference between the original settlement amount allocated to those payments and the lump sum you receive — may be taxable.
In practice, most sellers don't owe tax because they receive less than the original settlement value. But if you originally received a very large settlement at a favorable annuity rate, consult a tax professional before selling to avoid unexpected liability.
Alternatives to selling your structured settlement
Before committing to a factoring transaction, explore these lower-cost options:
- Structured settlement loan. Some lenders offer short-term loans secured by your future payments. You keep the payments and repay the loan from them. Interest rates are high — typically 15-25% — but you don't permanently give up your payment stream.
- Hybrid at the time of original settlement. If you're still negotiating your original settlement, ask for a partial lump sum upfront with the remainder structured. This is far cheaper than selling later.
- Hardship exemption programs. Some life insurance companies that administer annuities have hardship provisions that allow early, penalty-free withdrawals in extreme circumstances (terminal illness, natural disaster). Contact the annuity issuer directly.
- Government assistance programs. If the immediate need is medical or housing, federal and state programs may cover the gap without requiring you to sacrifice future settlement income.
How to negotiate which option you receive
In most personal injury cases, the choice between a structured settlement and a lump sum is negotiable. Here's how to approach it:
- Discuss early. Bring up the payout structure during settlement negotiations, not after.
- Know your leverage. Defendants often prefer structured settlements because they cost less upfront. You can use that to negotiate a higher total value.
- Work with a financial advisor. An advisor can help you model the long-term value of each option and present a compelling case to the insurer.
- Consider a hybrid. You can take a partial lump sum for immediate needs and structure the rest for future income.
- Get it in writing. The settlement agreement must clearly state the payout method. Have your attorney review it.
If you're still evaluating your claim, understanding the full value is critical. Learn more about how much is my personal injury claim worth to set realistic expectations.
Your settlement value depends on two main categories of damages. Read about economic vs non-economic damages to understand what you can claim.
Non-economic damages like pain and suffering damages can significantly affect your total compensation.
Comparing long-term financial outcomes
The long-term value of a structured settlement versus a lump sum depends on several factors, including investment returns and inflation. A structured settlement offers guaranteed payments, while a lump sum gives you the potential for higher growth but with risk.
For example, a $500,000 structured settlement paying $2,500 per month for 20 years totals $600,000. That's a 20% increase over the original amount, but the payments are fixed and may lose purchasing power over time.
If you invest a $500,000 lump sum at a 7% annual return, it could grow to over $1.9 million in 20 years. However, market downturns could reduce that value significantly, and you must pay taxes on investment gains.
Using a table to compare outcomes
| Factor | Structured Settlement | Lump Sum |
|---|---|---|
| Guaranteed income | Yes, fixed schedule | No, depends on investments |
| Tax treatment | All payments tax-free | Principal tax-free; gains taxable |
| Inflation protection | Often none without COLA | Potential for growth |
| Flexibility | Low, cannot change schedule | High, full control |
| Risk of loss | Low, insurer guarantees | High, market fluctuations |
| Creditor protection | Strong in most states | Weak, subject to seizure |
This table highlights the key trade-offs. A structured settlement prioritizes security and tax benefits, while a lump sum prioritizes flexibility and potential growth.
Your personal risk tolerance and financial goals should guide your choice. If you value predictability, a structured settlement is safer. If you are comfortable with risk, a lump sum may offer higher rewards.
How to evaluate your personal situation
Before deciding, assess your current financial health and future needs. Start by listing your monthly expenses, including medical costs, housing, and living expenses.
Next, consider your income sources. Do you have a job, disability benefits, or other income? If you rely solely on the settlement, a structured settlement provides a steady paycheck.
Then, think about your financial discipline. Have you successfully managed large sums of money before? If not, a structured settlement may be safer.
Questions to ask yourself
- Do I have ongoing medical needs that require regular payments?
- Am I comfortable managing investments and paying taxes on gains?
- Do I have high-interest debt that needs immediate payoff?
- What is my life expectancy given my injury?
- Do I have dependents who need financial support after my death?
Answering these questions can clarify which option aligns with your priorities. For example, if you have young children, a structured settlement with beneficiary provisions ensures they receive payments if you pass away.
If you are debt-free and financially savvy, a lump sum might allow you to build wealth faster. Always consult a financial advisor to run the numbers for your specific situation.
Understanding the role of inflation in your decision
Inflation erodes the purchasing power of fixed payments over time. A structured settlement with no cost-of-living adjustment (COLA) will buy less in 20 years than it does today.
For instance, $2,000 per month today might cover rent, but in 20 years, it may only cover a fraction of that cost. If inflation averages 3% annually, the real value of that payment drops by nearly half over two decades.
Some structured settlements include a COLA rider that increases payments annually by a fixed percentage, like 2% or 3%. This helps maintain purchasing power but reduces initial payment amounts.
With a lump sum, you can invest in assets that historically outpace inflation, such as stocks or real estate. This gives you a better chance of preserving or growing your wealth over the long term.
However, investment returns are not guaranteed, and poor market conditions could leave you worse off. Weighing inflation risk is a critical part of the structured settlement vs lump sum debate.
How state laws affect your settlement choice
State laws can influence whether a structured settlement or lump sum is available or advisable. Some states have specific rules for minors, requiring court approval for any settlement structure.
For example, in California, all settlements for minors must be approved by a judge, who often prefers structured settlements to protect the child's future. Other states may allow lump sums but with strict oversight.
Additionally, state laws on creditor protection vary. In some states, structured settlement payments are fully exempt from creditors, while lump sums may be partially protected or not protected at all.
If you are concerned about bankruptcy or lawsuits, a structured settlement may offer stronger safeguards. Consult with a local attorney to understand your state's specific laws before deciding.
Your attorney can also help negotiate terms that comply with state requirements while maximizing your benefits. This is another reason to involve legal counsel early in the process.
Psychological factors in settlement decisions
The emotional impact of receiving a large sum of money can be overwhelming. Many people feel a sense of relief and freedom, which can lead to impulsive spending.
Studies show that lottery winners and settlement recipients often report higher rates of financial regret within a few years. The sudden wealth can strain relationships and create new pressures.
A structured settlement can mitigate these psychological risks by providing a steady, predictable income. You avoid the temptation to splurge and can focus on long-term financial planning.
On the other hand, some people feel empowered by having full control over their money. If you are disciplined and have a solid plan, a lump sum can provide a sense of autonomy and achievement.
Consider your personality and past financial behavior. If you have a history of saving and investing wisely, a lump sum may work. If not, a structured settlement offers a safety net.
How to work with financial professionals
Making the right choice requires input from multiple experts. Start by hiring a personal injury attorney who understands settlement structures and can negotiate on your behalf.
Next, consult a certified financial planner (CFP) or a structured settlement consultant. They can run projections showing how each option would perform under different scenarios.
For example, a financial advisor might model a lump sum investment portfolio with a 6% return and compare it to a structured settlement with a 3% annuity rate. They can also factor in taxes, inflation, and your spending needs.
Finally, talk to a tax professional to understand the tax implications of each choice. This is especially important if your settlement includes taxable components like punitive damages.
Working with a team ensures you consider all angles and avoid costly mistakes. The upfront cost of professional advice is small compared to the potential long-term benefits.
Key takeaways
- Structured settlements offer guaranteed, tax-free income but lack flexibility.
- Lump sums give you immediate control but require discipline to avoid overspending.
- Both are generally tax-free for physical injury claims, but investment gains on a lump sum are taxable.
- Choose a structured settlement if you need long-term financial security or have concerns about managing money.
- Choose a lump sum if you are financially savvy, have immediate needs, or prefer simplicity.
- You can convert a structured settlement to a lump sum later, but it's expensive and requires court approval.
- Always consult an attorney and financial advisor before deciding.
Frequently asked questions
Is it better to take a structured settlement or lump sum?
What is the downside of a structured settlement?
Can you convert a structured settlement to a lump sum?
Are structured settlements taxable?
How long do structured settlement payments last?
This article is for general informational purposes only and does not constitute legal advice. Always consult a qualified professional about your specific circumstances.

Written & reviewed by
Can OTUConsumer Legal Information Researcher & Editor
Can OTU researches and edits every guide on this site, drawing on primary legal sources, court records, and state statutes to produce accurate, plain-English explanations of U.S. compensation and personal injury claims.
View all guides →